How to Maximize Your 401(k) in 2025-Strategies Every American Needs to Know

Retirement planning in 2025 is no longer an option—it’s a necessity. With inflation, rising interest rates, and global economic shifts affecting daily living costs, Americans are being urged to think strategically about their long-term financial security. Among the many retirement planning options, the 401(k) remains one of the most powerful tools for wealth accumulation. However, the majority of employees still underutilize this valuable asset, often due to misinformation or lack of awareness. This guide is crafted to help every American worker—from new graduates to seasoned professionals—understand the best ways to optimize their 401(k) in 2025. With in-depth strategies tailored to today’s economy, you’ll learn how to build a strong retirement portfolio while taking full advantage of tax benefits and employer incentives.

📅 Published: 2025-05-30 ✏️ Updated: 2025-05-30 ⏱ 9 min read 📝 1,765 words 👁 0 views
How to Maximize Your 401(k) in 2025-Strategies Every American Needs to Know

Retirement planning in 2025 is no longer an option—it’s a necessity. With inflation, rising interest rates, and global economic shifts affecting daily living costs, Americans are being urged to think strategically about their long-term financial security. Among the many retirement planning options, the 401(k) remains one of the most powerful tools for wealth accumulation. However, the majority of employees still underutilize this valuable asset, often due to misinformation or lack of awareness. This guide is crafted to help every American worker—from new graduates to seasoned professionals—understand the best ways to optimize their 401(k) in 2025. With in-depth strategies tailored to today’s economy, you’ll learn how to build a strong retirement portfolio while taking full advantage of tax benefits and employer incentives.

1. Max Out Your 401(k) Contributions to Build Wealth Faster

In 2025, the IRS has increased the annual contribution limit to $23,000 for individuals under 50, and $30,500 for those aged 50 and over, including catch-up contributions. These higher thresholds allow you to significantly boost your retirement nest egg if you contribute consistently. Even if you can't afford the maximum right now, aim to contribute at least 15–20% of your pre-tax income. Not only does this reduce your taxable income today, but it also leverages the power of compound interest for future growth. A consistent contribution strategy—especially when automated—ensures discipline, builds momentum, and minimizes the temptation to divert funds elsewhere. Prioritizing retirement savings early in your career helps you stay ahead of inflation and ensures your money works for you 24/7. Think of your 401(k) not as a savings account, but as a personal pension fund designed to secure your future lifestyle.

2. Never Leave Free Money on the Table: Use the Employer Match

One of the biggest missed opportunities in retirement planning is failing to take advantage of the employer match. In 2025, more companies are offering enhanced matching contributions, with some matching up to 100% of the first 5–6% of your salary. That’s essentially free money added to your retirement savings just for participating. Yet, millions of Americans contribute below the threshold required to qualify for the full match. This mistake can cost you tens of thousands of dollars over time. Always check your company’s match policy and contribute at least the amount required to get the full benefit. It's an immediate 100% return on your investment—something rarely found in any financial market. Missing out on this is like rejecting a raise. Taking full advantage of the employer match not only accelerates your savings but shows financial savvy that pays off in both the short and long term.

3. Smart Diversification: Spread Risk and Maximize Growth

Diversification in 2025 isn’t just about owning multiple assets—it’s about strategic allocation that aligns with economic forecasts, market cycles, and your personal risk profile. With geopolitical uncertainty, tech volatility, and shifting interest rates, blindly putting all your funds into one asset class is a dangerous game. Most 401(k) plans offer a mix of mutual funds, index funds, bonds, and international equities. A well-diversified portfolio reduces risk and ensures steady growth across varying market conditions. Younger investors can afford to lean into higher-growth assets like tech or emerging markets, while older participants should start shifting toward stability through bonds and dividend-paying funds. Diversification also protects you against inflation and currency depreciation. Rebalancing annually ensures your portfolio stays aligned with your financial goals. In short, diversification isn’t just a buzzword—it’s your first defense against market unpredictability and your ticket to long-term growth.

4. Add a Roth 401(k) for Tax-Free Future Income

The Roth 401(k) is gaining serious traction in 2025, and for good reason. Unlike traditional 401(k)s, contributions to a Roth are made with after-tax dollars, but withdrawals—including growth—are completely tax-free in retirement. This can be a game-changer for those who expect to be in a higher tax bracket later in life or believe tax rates will increase in the future. Many companies now offer both traditional and Roth 401(k) options, giving you flexibility. By splitting your contributions between the two, you can create a tax-diversified retirement portfolio. This strategy provides more control over your future tax liability, letting you manage your income withdrawals more efficiently. It also helps you hedge against changes in tax policy or unexpected financial needs. If your employer offers Roth contributions and you’re in a lower tax bracket now, strongly consider shifting some or all of your contributions to Roth for long-term advantage.

5. Don’t Sabotage Your Retirement: Avoid Early Withdrawals

One of the most damaging mistakes people make with their 401(k) is withdrawing funds before retirement. Unless you meet a very narrow set of hardship criteria, early withdrawals come with a 10% penalty plus regular income tax—potentially wiping out up to 30–40% of what you take out. In 2025, with inflation putting pressure on everyday budgets, some may be tempted to dip into their retirement savings. Resist that urge. Your 401(k) should be viewed as untouchable until age 59½ at minimum. If you’re in a financial bind, look to Roth IRA contributions, emergency funds, or low-interest credit options first. Borrowing from your 401(k) can seem harmless but often leads to missed market growth and repayment issues. Instead, treat your retirement account like a locked vault. The money in it is not for now—it’s your future paycheck, and every early withdrawal is a deduction from your retirement lifestyle.

6. Use Technology: Target-Date Funds and Robo-Advisors

In 2025, technology is your retirement ally. Target-date funds remain a solid choice for hands-off investors, automatically adjusting your asset allocation based on your planned retirement year. For those who want more personalization, robo-advisors now integrate with many 401(k) platforms, using AI algorithms to analyze your goals, risk tolerance, and economic conditions. These tools help optimize returns while minimizing human error. Best of all, they usually come with very low management fees. Whether you're a beginner or experienced investor, digital tools provide real-time portfolio tracking, automatic rebalancing, and insights that would take hours to research manually. By leveraging fintech in your 401(k) strategy, you can make smarter decisions, minimize guesswork, and stay ahead of market changes. Don’t ignore these modern tools—they are designed to enhance your financial security while simplifying investment management.

7. Rebalance Annually to Stay Aligned with Goals

Your 401(k) is not a “set it and forget it” account—it evolves with the market, and so should your strategy. Over time, certain investments in your portfolio may outperform others, skewing your intended allocation. For example, if your stocks perform very well, your portfolio might become too aggressive without you even realizing it. Rebalancing once a year brings your investments back to their original proportions, helping manage risk and preserve gains. Many modern plans offer automatic rebalancing, but it’s still wise to review your portfolio manually. Rebalancing also gives you a chance to re-evaluate your goals and adjust based on changes in income, expenses, or risk tolerance. It’s a disciplined way to buy low and sell high—essentially locking in gains without needing market timing. In 2025’s fast-moving economy, staying proactive about your allocation ensures your retirement plan stays on track.

8. Consolidate Old 401(k)s to Simplify and Save

If you’ve switched jobs more than once, chances are you have multiple 401(k)s sitting in different accounts. In 2025, consolidating these accounts is easier than ever and comes with major benefits. First, it simplifies management—you’ll have one dashboard to monitor performance and make investment decisions. Second, it reduces administrative fees and paperwork, which over time can save you thousands. Lastly, consolidating into one account ensures consistent asset allocation, avoiding overlaps or contradictory investment strategies. You can choose to roll them into your current 401(k) plan or move them into an IRA for greater control and investment options. Either way, it’s better than letting old accounts sit forgotten, possibly in high-fee funds. Keeping your retirement assets centralized helps you make more informed decisions and builds a clearer picture of your financial future.

9. Cut Hidden Costs: Choose Low-Fee Funds

High fees can silently erode your retirement savings. Even a 1% difference in fund expenses can reduce your total savings by over $100,000 over a 30-year period. In 2025, most 401(k) plans offer access to low-cost index funds and ETFs with expense ratios under 0.10%. Always review your plan's available investment options and opt for the lowest-cost funds that still match your desired allocation. Ask your HR department or plan administrator if you're unsure. Avoid actively managed funds unless they consistently outperform the market after fees, which is rare. Many financial platforms now provide fee comparison tools to help you choose smarter. Reducing fees is like giving yourself a raise—it boosts your returns without requiring you to save more or take on more risk. Over time, this simple shift can dramatically increase your retirement wealth.

10. Consult a Fiduciary Advisor for Personalized Guidance

As you get closer to retirement—or if you’re just overwhelmed by options—consider working with a fiduciary financial advisor. Unlike brokers, fiduciary advisors are legally required to act in your best interest. In 2025, many of these professionals offer hybrid services combining human expertise with AI-powered tools. They can help you create a personalized strategy, optimize your withdrawal plan, and minimize taxes in retirement. Advisors also help coordinate Social Security, Medicare, and estate planning with your 401(k) goals. Look for fee-only advisors who charge by the hour or based on assets managed, avoiding those who earn commissions on products. A good advisor doesn’t just manage your money—they give you peace of mind, confidence, and a plan that adapts as your life changes. Think of them as your retirement coach, helping you stay on track and maximize every dollar you've worked so hard to save.

Conclusion

Maximizing your 401(k) in 2025 is more than just making regular contributions—it’s about taking strategic actions that align with the new economic realities. From increasing your savings rate and using employer matches, to diversifying smartly, avoiding fees, and planning for tax efficiency, every decision counts. The earlier you apply these principles, the greater your long-term financial security will be. With today’s advanced tools, flexible plan options, and evolving tax landscape, the path to retirement success is clearer—but only if you take it seriously. Use this year to audit, optimize, and enhance your 401(k) strategy. Your future self will thank you.
Dfluxspace Research Team

This article has been researched, reviewed and published by the Dfluxspace Research Team.

Last Reviewed: 2025-05-30

Global Leadership in Business-What Worked for Past Icons What Modern CEOs Do Differently and How AI Will Redefine Leadership

Global Leadership in Business-What Worked for Past Icons What Modern CEOs Do Differently and How AI Will Redefine Leadership

Global leadership in business has always been a fascinating subject because it connects the past, present, and future of how organizations grow and adapt. Yesterday’s business icons, from Andrew Carnegie to Steve Jobs, built their empires through visionary thinking, resilience, and groundbreaking innovations that disrupted entire industries. They created legacies by setting standards in production, distribution, and consumer experiences that shaped the modern business landscape. Today, leadership has evolved to meet the challenges of globalization, digital transformation, and shifting employee expectations. Modern CEOs are not only expected to generate profits but also to align their companies with social responsibility, sustainability, and inclusivity. Unlike leaders of the past who often followed rigid hierarchies, today’s executives must build flexible, agile teams that thrive in uncertain environments. The rise of remote work, technology-driven decision-making, and digital-first strategies has reshaped what it means to lead effectively. At the same time, the future promises even more transformation with artificial intelligence poised to redefine leadership altogether. From AI-driven insights to virtual leaders, tomorrow’s leadership models may look radically different. To fully understand this evolution, it is essential to analyze the lessons from the past, the approaches used by today’s CEOs, and the potential impact AI will have on the global business environment. This comprehensive playbook will help professionals, entrepreneurs, and future leaders navigate leadership across timelines.

How Can Businesses Expand Globally Without Huge Investment?

How Can Businesses Expand Globally Without Huge Investment?

Global expansion is no longer reserved for multinational corporations with massive budgets. In today’s digital era, even small and medium-sized enterprises (SMEs) can access international markets without huge investments. The rise of e-commerce, digital marketing, and remote business models has lowered barriers significantly. Businesses can leverage online platforms, marketplaces, and social media to reach customers worldwide. Strategic planning, cost-effective tools, and smart partnerships are key to scaling internationally. Understanding target markets, cultural nuances, and regulatory requirements prevents costly mistakes. Companies must prioritize digital presence, customer service, and supply chain optimization. Cloud-based technologies reduce infrastructure costs while enabling global operations. Outsourcing and collaboration with local partners further cut down financial burdens. Businesses can start small, test the market, and gradually scale up. Exporting digital products or services reduces logistics and inventory expenses. Digital payment systems facilitate international transactions securely and efficiently. Market research, competitor analysis, and local trends guide successful entry strategies. SEO, content marketing, and social media allow businesses to attract international audiences organically. Global expansion also requires compliance with taxes, customs, and data privacy laws. Strategic pricing and shipping solutions improve competitiveness. Continuous performance tracking and feedback collection enhance market adaptation. In summary, with the right strategy and digital tools, businesses can go global efficiently and sustainably without huge capital outlay.

How Can You Use Waste Iron and Scrap Metal for a Lucrative Side Business?

How Can You Use Waste Iron and Scrap Metal for a Lucrative Side Business?

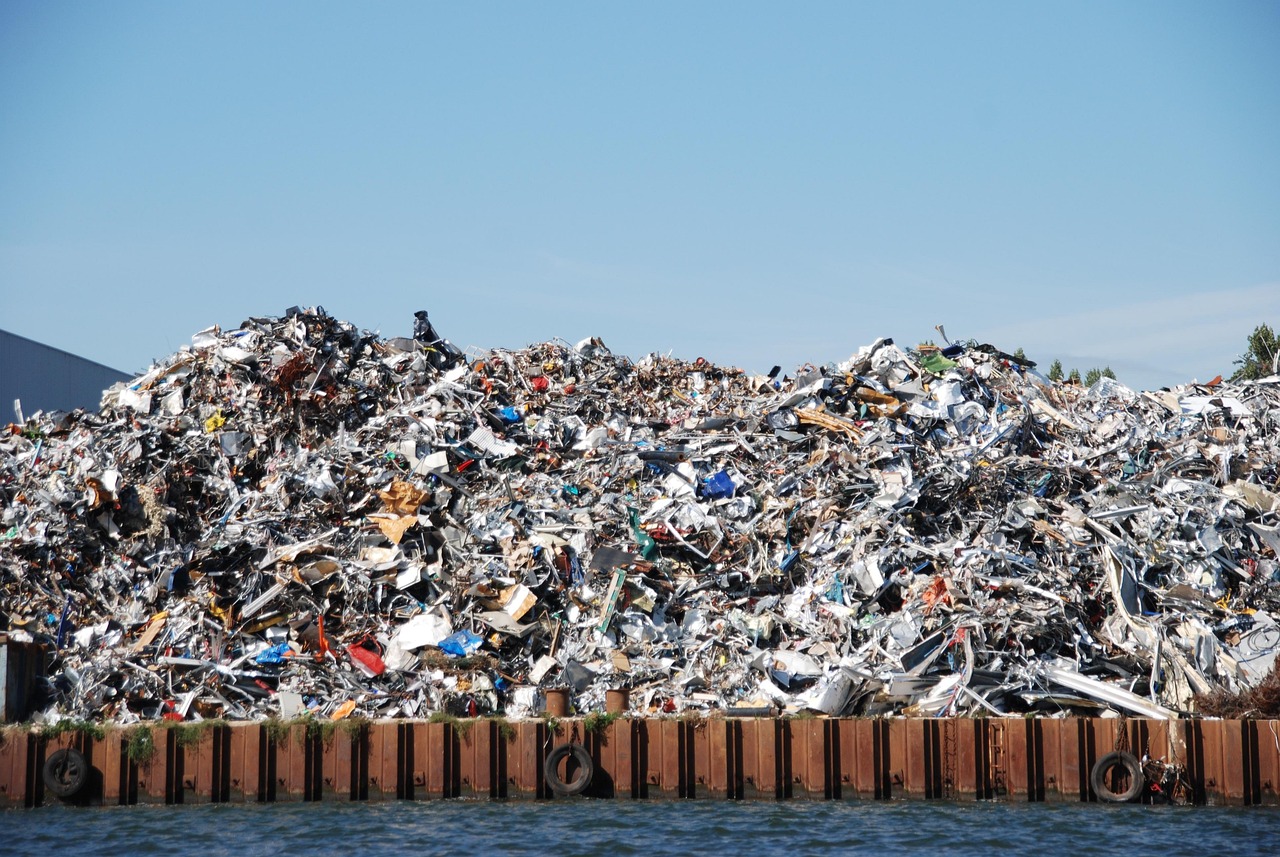
Waste iron and scrap metal are often treated as useless by-products of construction, manufacturing, or household usage, but in reality, they are untapped treasures for entrepreneurs who want to build a profitable side business. The modern economy places high importance on sustainability, recycling, and resource optimization, which means that what one person discards as waste can actually become another person’s income-generating asset. Every piece of waste iron—whether it’s from old machines, household appliances, demolished buildings, or broken automobiles—carries inherent value that can be unlocked through collection, processing, and resale. By tapping into this opportunity, entrepreneurs not only create revenue streams but also contribute to reducing environmental pollution, supporting the circular economy, and aligning with global green business practices. Starting a side business in waste iron and scrap metal does not require a massive upfront investment. With as little as basic tools, storage space, and a network to source and sell scrap, individuals can slowly scale up their efforts into a structured operation. Unlike businesses that require specialized degrees or advanced technical expertise, scrap metal recycling thrives on awareness, consistency, and connections within the local community. For example, a person who understands where to source unused iron rods, machinery parts, or metal furniture can directly sell them to recycling units for cash. Over time, with proper planning, the same entrepreneur can expand into melting, processing, or exporting scrap iron to high-demand industries. This business is lucrative because steel and iron are endlessly recyclable. Unlike other raw materials that degrade over time, metals retain their strength and durability even after multiple recycling cycles. This means the global demand for recycled iron will always remain high, especially in construction, automobile manufacturing, and infrastructure projects where iron-based materials are essential. From a financial perspective, dealing in scrap metal also provides steady cash flow because buyers—such as local scrap yards, recycling centers, and export companies—pay upfront for the raw material. For people looking to create side businesses that are both practical and profitable, waste iron recycling presents an unmatched opportunity. It offers scalability, environmental impact, and the ability to transition from small side hustle to full-fledged business. In the following sections, we’ll explore step-by-step how entrepreneurs can start, manage, and scale this opportunity into a sustainable income source.

How Have Businesses Earned Passive Income by Providing EV Charging Conversion Services?

How Have Businesses Earned Passive Income by Providing EV Charging Conversion Services?

The electric vehicle (EV) industry is growing at an unprecedented pace, creating lucrative opportunities for entrepreneurs. As EV adoption accelerates, charging infrastructure and vehicle conversion services are emerging as essential business avenues. EV charging stations are critical for supporting the expanding fleet of electric cars, trucks, and two-wheelers. Conversion services allow traditional internal combustion engine (ICE) vehicles to switch to electric power, offering sustainability solutions. Businesses in these sectors can earn passive income by leveraging technology and infrastructure investments. EV charging services generate recurring revenue through user fees, subscription plans, and partnerships. Conversion services attract customers seeking cost-effective and eco-friendly alternatives to buying new EVs. The demand for EV solutions is driven by government incentives, environmental policies, and consumer preferences. Companies providing these services are positioned to benefit from long-term growth trends. EV charging and conversion businesses often require initial investment, but revenue models ensure steady returns. The sector also benefits from partnerships with local governments, utilities, and automobile manufacturers. Strategic placement of EV charging stations maximizes usage and profitability. Innovative pricing models such as pay-per-use or monthly subscriptions attract diverse customer groups. Conversion services can generate income from labor charges, parts supply, and maintenance contracts. Recurring contracts with fleet operators and commercial clients ensure stable cash flow. Advances in battery technology and conversion kits lower costs and increase accessibility. Integration with smart grids and renewable energy sources enhances service value. Digital platforms and apps enable easy access, reservations, and payment, boosting usage. This guide explores ten business models that generate passive income in EV charging and conversion services. Each section offers practical strategies for sustainable revenue growth.

How Small Businesses Expanded Internationally with Limited Budgets

How Small Businesses Expanded Internationally with Limited Budgets

Expanding internationally is often seen as something only large corporations with millions of dollars can achieve, but small businesses across the globe have proven that with the right strategies, even limited budgets can take them across borders. Many entrepreneurs initially believe that entering foreign markets requires costly offices, legal teams, and advertising campaigns, but the digital era has changed that perception entirely. Through smart planning, resource optimization, and technology-driven approaches, local ventures have managed to tap into global markets with minimal investment. The secret lies not in money, but in creativity, research, and consistency. Entrepreneurs who succeed globally don’t waste resources—they leverage free or low-cost digital tools, government programs, outsourcing, and collaborations. For example, platforms like Shopify, Etsy, and Amazon have allowed small sellers to reach customers in dozens of countries without renting a single foreign store. Similarly, social media and content marketing have enabled unknown businesses to build trust and recognition in regions where big brands dominate. Instead of traditional expensive marketing campaigns, small businesses focused on niche targeting, personalized services, and unique value propositions. They built loyal customer bases by solving problems big companies often ignored. The most inspiring part is that these businesses did not wait for perfect conditions; they experimented, learned from failures, and grew gradually. This article explores real, step-by-step strategies small businesses used to expand internationally on a shoestring budget, showing how resourceful planning can beat financial limitations. By the end, you will see that you don’t need millions to go global—you just need the right roadmap and determination.

Hudson Global Now Star Equity Holdings – What Investors Need to Know

Hudson Global Now Star Equity Holdings – What Investors Need to Know

Why Rebranding Matters in Today’s Financial Market: In the world of finance, rebranding is not just a matter of logos, names, or colors—it’s about signaling transformation, repositioning strategy, and reshaping how a company communicates with its investors and stakeholders. The recent rebranding of Hudson Global into Star Equity Holdings has captured attention worldwide, particularly among investors seeking clarity on what this shift means for future growth, business direction, and shareholder value. Rebranding in corporate finance often goes beyond marketing; it is deeply tied to business realignment, mergers, acquisitions, or diversification into new markets. Investors are increasingly aware that a name change reflects broader structural moves, and Hudson Global’s evolution into Star Equity Holdings is no different. On September 2025, this news has generated search buzz as analysts, traders, and global audiences ask: Why now? and What’s next? Understanding the significance of this rebranding is crucial for those tracking investment opportunities and long-term financial strategies in today’s fast-changing market landscape.