Stablecoins and Banking 2-0-How Digital Assets Are Reshaping Global Finance

The financial world has witnessed countless revolutions, from the invention of coins and paper money to the rise of stock markets and credit cards, yet none has been as disruptive in recent years as the rise of digital assets. Among these, stablecoins stand out as a transformative force, bridging the gap between traditional banking and the future of decentralized finance. Stablecoins are digital tokens pegged to fiat currencies like the U.S. dollar, euro, or even commodities such as gold, offering the stability of traditional money with the efficiency of blockchain technology. For ordinary consumers, businesses, and even governments, the emergence of stablecoins signals the dawn of what many are calling “Banking 2.0.” This concept reflects a shift toward faster, borderless, more inclusive financial systems where traditional barriers are minimized, and innovation thrives. As the global economy wrestles with inflation, high transaction costs, and cross-border payment inefficiencies, stablecoins provide practical answers to problems that banks and regulators have struggled to solve for decades. The question now is not whether stablecoins will reshape finance but how quickly and in what form this transition will occur. In this blog post, we will explore the rise of stablecoins, their real-world applications, the concerns they raise, and their potential to redefine how the world saves, spends, and invests in the decades ahead.

📅 Published: 2026-08-26 ✏️ Updated: 2026-08-26 ⏱ 9 min read 📝 1,771 words 👁 0 views
Stablecoins and Banking 2-0-How Digital Assets Are Reshaping Global Finance

The financial world has witnessed countless revolutions, from the invention of coins and paper money to the rise of stock markets and credit cards, yet none has been as disruptive in recent years as the rise of digital assets. Among these, stablecoins stand out as a transformative force, bridging the gap between traditional banking and the future of decentralized finance. Stablecoins are digital tokens pegged to fiat currencies like the U.S. dollar, euro, or even commodities such as gold, offering the stability of traditional money with the efficiency of blockchain technology. For ordinary consumers, businesses, and even governments, the emergence of stablecoins signals the dawn of what many are calling “Banking 2.0.” This concept reflects a shift toward faster, borderless, more inclusive financial systems where traditional barriers are minimized, and innovation thrives. As the global economy wrestles with inflation, high transaction costs, and cross-border payment inefficiencies, stablecoins provide practical answers to problems that banks and regulators have struggled to solve for decades. The question now is not whether stablecoins will reshape finance but how quickly and in what form this transition will occur. In this blog post, we will explore the rise of stablecoins, their real-world applications, the concerns they raise, and their potential to redefine how the world saves, spends, and invests in the decades ahead.

1. What Are Stablecoins and Why Are They Different from Other Cryptocurrencies?

Stablecoins are digital currencies designed to maintain a stable value by being pegged to a reserve asset such as the U.S. dollar, euro, or gold. Unlike volatile cryptocurrencies like Bitcoin or Ethereum, which can swing in value dramatically within hours, stablecoins are engineered to provide predictability. This stability makes them attractive for everyday use, such as payments, savings, and remittances. Traditional cryptocurrencies are often viewed as speculative assets, while stablecoins aim to function as reliable mediums of exchange. For businesses, stablecoins offer faster settlement times compared to wire transfers or credit card systems. For individuals, they provide the convenience of sending money across borders within minutes instead of days. Moreover, stablecoins are built on blockchain networks, meaning transactions are transparent, secure, and easily verifiable. This unique combination of stability and efficiency is what sets them apart, making them a cornerstone of the next phase of digital finance.

2. How Do Stablecoins Work in Practice?

Stablecoins function by maintaining reserves that back their value. For instance, a U.S. dollar–pegged stablecoin is typically backed by actual cash reserves or equivalent short-term securities such as U.S. Treasuries. This ensures that each token issued can be redeemed for one dollar, maintaining its stability. The most common types of stablecoins are fiat-backed (like USDC or USDT), crypto-backed (like DAI, which is overcollateralized with other cryptocurrencies), and algorithmic stablecoins, which rely on supply-demand mechanics to stabilize value. When someone buys a stablecoin, they exchange their fiat currency for the token, which is then stored in their digital wallet. When they redeem it, the issuing company burns the tokens and provides the fiat back. This transparent, rules-based system ensures that stablecoins can maintain value while allowing seamless transactions across global financial networks. Unlike banks that may require intermediaries, paperwork, and long processing times, stablecoins move instantly across blockchains, redefining the user experience of money itself.

3. Why Are Stablecoins Called “Banking 2.0”?

Stablecoins are often labeled as “Banking 2.0” because they represent the modernization of core banking services—payments, lending, and savings—on decentralized rails. Traditional banks are limited by legacy infrastructure, slow settlement systems, and geographical boundaries. Stablecoins, however, operate globally, 24/7, without restrictions of time zones or international borders. Sending $100 across the world using a bank wire can take three to five days with high fees, while the same transfer with a stablecoin can be nearly instant and cost less than a dollar. Furthermore, stablecoins unlock new models of financial services, such as decentralized lending platforms where users can borrow and lend without traditional banks. By integrating with digital wallets and decentralized apps, stablecoins democratize access to financial services, particularly in regions where banking infrastructure is weak or nonexistent. This seamless, user-friendly, and inclusive approach is why many experts view stablecoins as the future of banking.

4. How Do Stablecoins Improve Cross-Border Payments?

Cross-border payments have long been plagued by inefficiencies, including high fees, multiple intermediaries, and long settlement times. Migrant workers sending remittances often lose 5–10% of their income to transaction costs. Stablecoins present a breakthrough solution by eliminating these inefficiencies. A user in the U.S. can send USDC to a family member in Asia within minutes, and the recipient can convert it into local currency through an exchange or use it directly where accepted. The blockchain ensures transparency, making fraud and double spending nearly impossible. Moreover, stablecoins offer predictable value—something volatile cryptocurrencies cannot guarantee. Global companies are also beginning to use stablecoins for international trade settlements, reducing dependency on costly correspondent banking systems. In this way, stablecoins not only reduce costs but also create financial inclusion for millions of people around the world who previously struggled with access to efficient cross-border money transfers.

5. What Role Do Stablecoins Play in Decentralized Finance (DeFi)?

Stablecoins are the backbone of the rapidly expanding DeFi ecosystem. Platforms like Aave, Compound, and MakerDAO rely on stablecoins to provide lending, borrowing, and yield farming services without intermediaries. Users can deposit stablecoins into decentralized lending pools to earn interest or borrow against their holdings instantly. Unlike traditional banks, DeFi platforms operate without paperwork, credit checks, or intermediaries, enabling anyone with internet access to participate. Stablecoins provide the necessary stability for these financial products to function reliably. For example, instead of lending volatile Bitcoin, which could lose 10% of its value overnight, users can lend stablecoins pegged to the dollar, ensuring predictability. This synergy between stablecoins and DeFi is unlocking a parallel financial system that runs 24/7, is globally accessible, and is reshaping how people interact with money and investments.

6. What Are the Risks and Concerns Surrounding Stablecoins?

Despite their promise, stablecoins face significant concerns. The first is regulatory uncertainty. Governments worry about systemic risks if stablecoins grow too large without oversight. If reserves are mismanaged, a collapse could destabilize financial markets, similar to bank runs. The second concern is transparency: not all issuers fully disclose whether their reserves are sufficient and liquid. Algorithmic stablecoins, such as TerraUSD, have already demonstrated catastrophic failures that wiped out billions in value. Cybersecurity threats and fraud risks also loom, as hackers target digital wallets and exchanges. Additionally, critics argue that widespread stablecoin adoption could undermine monetary policy, reducing central banks’ control over money supply. These risks highlight the importance of robust regulation and industry standards to ensure stablecoins are safe, transparent, and resilient as they grow in influence.

7. How Are Governments and Regulators Responding to Stablecoins?

Global regulators are increasingly paying attention to stablecoins, recognizing both their potential and their risks. In the United States, agencies like the SEC, Treasury Department, and Federal Reserve are debating how to classify and regulate them. Europe has introduced the Markets in Crypto-Assets (MiCA) framework, which sets clear rules for stablecoin issuers, while countries like Singapore and Japan are also advancing regulation. Some governments view stablecoins as competition to central bank digital currencies (CBDCs), while others see them as complementary. The challenge lies in creating regulations that ensure consumer protection without stifling innovation. Billions of dollars already flow through stablecoins daily, making it clear that governments cannot ignore them. Regulation is not just about safety but also about integrating stablecoins into the broader financial system responsibly, allowing innovation while maintaining financial stability.

8. Could Stablecoins Replace Traditional Banks?

Stablecoins are unlikely to completely replace banks but will certainly challenge and reshape how banks operate. Banks provide more than just payments; they also offer loans, savings accounts, and investment services. Stablecoins, however, are already proving superior in payments and cross-border transactions. Some experts predict that banks may adopt stablecoin technology themselves, integrating blockchain-based settlement systems into their operations. Others believe banks could lose relevance if they fail to adapt. In essence, stablecoins won’t entirely eliminate banks but will force them to modernize, improve efficiency, and lower fees. The winners in this new landscape will be those that embrace technology and partner with fintech innovators to deliver the speed and transparency customers demand.

9. How Do Stablecoins Compare to Central Bank Digital Currencies (CBDCs)?

Stablecoins and CBDCs may seem similar, but they differ fundamentally. Stablecoins are issued by private companies and backed by fiat or crypto assets, while CBDCs are issued directly by governments and central banks. Stablecoins offer innovation, flexibility, and fast adoption, while CBDCs provide government-backed stability and legal tender status. Many analysts believe the future will see both coexist: CBDCs serving as the official digital currency, and stablecoins filling niche roles in DeFi, cross-border payments, and financial innovation. In fact, some governments may use stablecoin frameworks to accelerate their CBDC launches. The interplay between the two will shape the future of digital finance and determine how money evolves in the digital era.

10. What Does the Future of Stablecoins Look Like in Global Finance?

The future of stablecoins is bright but depends on three key factors: regulatory clarity, technological advancements, and user adoption. If regulators strike the right balance, stablecoins could become mainstream tools for savings, payments, and investment. Businesses may adopt stablecoins as standard for cross-border trade, reducing reliance on the dollar in international settlements. Retail users may increasingly use stablecoins in digital wallets, replacing cash and credit cards for everyday transactions. On the other hand, failure to address risks like reserve transparency or cybersecurity could limit growth. With trillions of dollars in potential value at stake, stablecoins are positioned to be a cornerstone of global finance in the coming decades, ushering in the era of “Banking 2.0.”

Conclusion

Stablecoins represent one of the most profound shifts in financial history, offering stability, efficiency, and inclusivity at a time when traditional systems struggle to keep up with global demands. They are not just another crypto trend but a foundational tool for the future of money. By enabling instant cross-border payments, powering decentralized finance, and challenging traditional banks, stablecoins are paving the way for “Banking 2.0.” Yet their growth comes with challenges: regulatory scrutiny, systemic risks, and transparency concerns. Billions already flow daily through stablecoins, proving their relevance is no longer theoretical but practical and widespread. For businesses, investors, and ordinary consumers, understanding and adapting to this trend is crucial. The question is no longer whether stablecoins will reshape finance—it is how quickly they will transform the global financial landscape.
Dfluxspace Research Team

This article has been researched, reviewed and published by the Dfluxspace Research Team.

Last Reviewed: 2026-08-26

Global Leadership in Business-What Worked for Past Icons What Modern CEOs Do Differently and How AI Will Redefine Leadership

Global Leadership in Business-What Worked for Past Icons What Modern CEOs Do Differently and How AI Will Redefine Leadership

Global leadership in business has always been a fascinating subject because it connects the past, present, and future of how organizations grow and adapt. Yesterday’s business icons, from Andrew Carnegie to Steve Jobs, built their empires through visionary thinking, resilience, and groundbreaking innovations that disrupted entire industries. They created legacies by setting standards in production, distribution, and consumer experiences that shaped the modern business landscape. Today, leadership has evolved to meet the challenges of globalization, digital transformation, and shifting employee expectations. Modern CEOs are not only expected to generate profits but also to align their companies with social responsibility, sustainability, and inclusivity. Unlike leaders of the past who often followed rigid hierarchies, today’s executives must build flexible, agile teams that thrive in uncertain environments. The rise of remote work, technology-driven decision-making, and digital-first strategies has reshaped what it means to lead effectively. At the same time, the future promises even more transformation with artificial intelligence poised to redefine leadership altogether. From AI-driven insights to virtual leaders, tomorrow’s leadership models may look radically different. To fully understand this evolution, it is essential to analyze the lessons from the past, the approaches used by today’s CEOs, and the potential impact AI will have on the global business environment. This comprehensive playbook will help professionals, entrepreneurs, and future leaders navigate leadership across timelines.

How Can Businesses Expand Globally Without Huge Investment?

How Can Businesses Expand Globally Without Huge Investment?

Global expansion is no longer reserved for multinational corporations with massive budgets. In today’s digital era, even small and medium-sized enterprises (SMEs) can access international markets without huge investments. The rise of e-commerce, digital marketing, and remote business models has lowered barriers significantly. Businesses can leverage online platforms, marketplaces, and social media to reach customers worldwide. Strategic planning, cost-effective tools, and smart partnerships are key to scaling internationally. Understanding target markets, cultural nuances, and regulatory requirements prevents costly mistakes. Companies must prioritize digital presence, customer service, and supply chain optimization. Cloud-based technologies reduce infrastructure costs while enabling global operations. Outsourcing and collaboration with local partners further cut down financial burdens. Businesses can start small, test the market, and gradually scale up. Exporting digital products or services reduces logistics and inventory expenses. Digital payment systems facilitate international transactions securely and efficiently. Market research, competitor analysis, and local trends guide successful entry strategies. SEO, content marketing, and social media allow businesses to attract international audiences organically. Global expansion also requires compliance with taxes, customs, and data privacy laws. Strategic pricing and shipping solutions improve competitiveness. Continuous performance tracking and feedback collection enhance market adaptation. In summary, with the right strategy and digital tools, businesses can go global efficiently and sustainably without huge capital outlay.

How Can You Use Waste Iron and Scrap Metal for a Lucrative Side Business?

How Can You Use Waste Iron and Scrap Metal for a Lucrative Side Business?

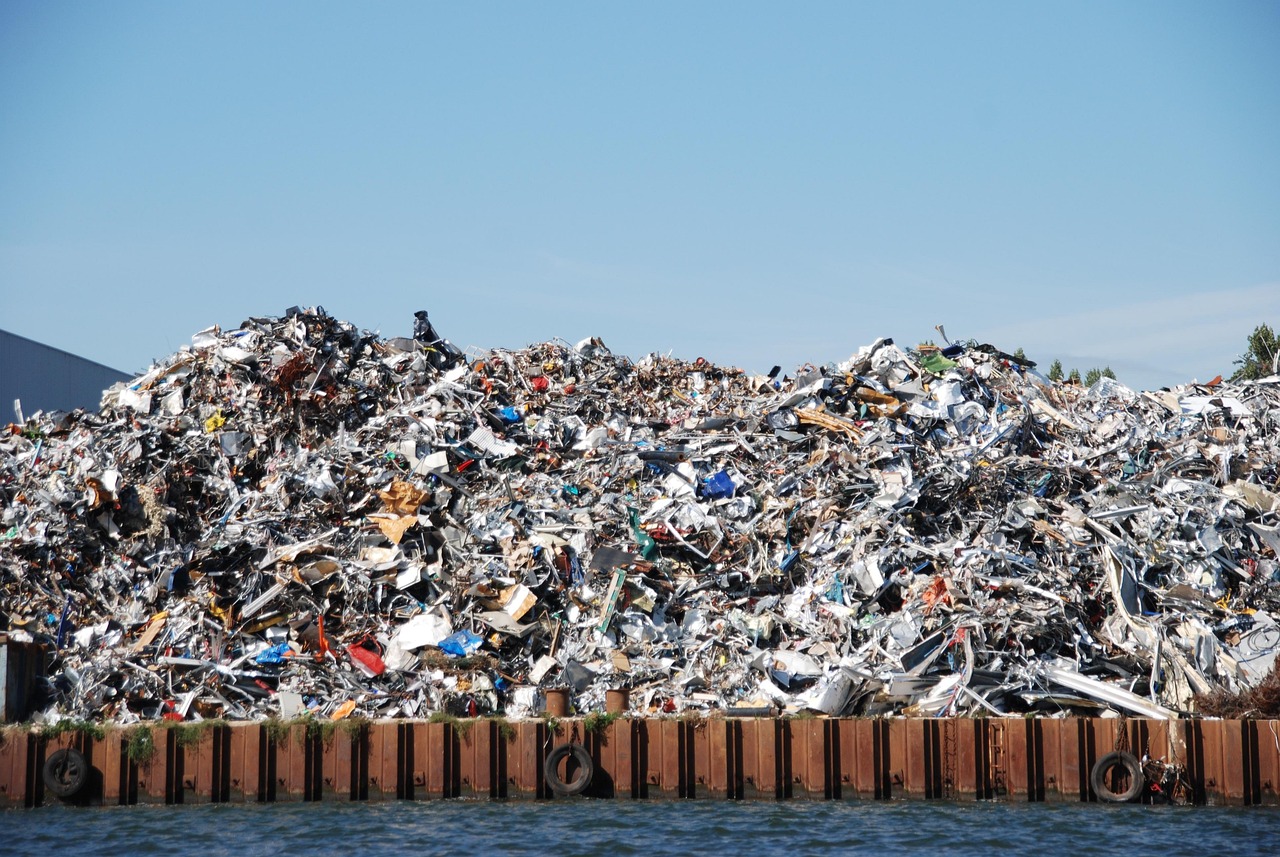
Waste iron and scrap metal are often treated as useless by-products of construction, manufacturing, or household usage, but in reality, they are untapped treasures for entrepreneurs who want to build a profitable side business. The modern economy places high importance on sustainability, recycling, and resource optimization, which means that what one person discards as waste can actually become another person’s income-generating asset. Every piece of waste iron—whether it’s from old machines, household appliances, demolished buildings, or broken automobiles—carries inherent value that can be unlocked through collection, processing, and resale. By tapping into this opportunity, entrepreneurs not only create revenue streams but also contribute to reducing environmental pollution, supporting the circular economy, and aligning with global green business practices. Starting a side business in waste iron and scrap metal does not require a massive upfront investment. With as little as basic tools, storage space, and a network to source and sell scrap, individuals can slowly scale up their efforts into a structured operation. Unlike businesses that require specialized degrees or advanced technical expertise, scrap metal recycling thrives on awareness, consistency, and connections within the local community. For example, a person who understands where to source unused iron rods, machinery parts, or metal furniture can directly sell them to recycling units for cash. Over time, with proper planning, the same entrepreneur can expand into melting, processing, or exporting scrap iron to high-demand industries. This business is lucrative because steel and iron are endlessly recyclable. Unlike other raw materials that degrade over time, metals retain their strength and durability even after multiple recycling cycles. This means the global demand for recycled iron will always remain high, especially in construction, automobile manufacturing, and infrastructure projects where iron-based materials are essential. From a financial perspective, dealing in scrap metal also provides steady cash flow because buyers—such as local scrap yards, recycling centers, and export companies—pay upfront for the raw material. For people looking to create side businesses that are both practical and profitable, waste iron recycling presents an unmatched opportunity. It offers scalability, environmental impact, and the ability to transition from small side hustle to full-fledged business. In the following sections, we’ll explore step-by-step how entrepreneurs can start, manage, and scale this opportunity into a sustainable income source.

How Have Businesses Earned Passive Income by Providing EV Charging Conversion Services?

How Have Businesses Earned Passive Income by Providing EV Charging Conversion Services?

The electric vehicle (EV) industry is growing at an unprecedented pace, creating lucrative opportunities for entrepreneurs. As EV adoption accelerates, charging infrastructure and vehicle conversion services are emerging as essential business avenues. EV charging stations are critical for supporting the expanding fleet of electric cars, trucks, and two-wheelers. Conversion services allow traditional internal combustion engine (ICE) vehicles to switch to electric power, offering sustainability solutions. Businesses in these sectors can earn passive income by leveraging technology and infrastructure investments. EV charging services generate recurring revenue through user fees, subscription plans, and partnerships. Conversion services attract customers seeking cost-effective and eco-friendly alternatives to buying new EVs. The demand for EV solutions is driven by government incentives, environmental policies, and consumer preferences. Companies providing these services are positioned to benefit from long-term growth trends. EV charging and conversion businesses often require initial investment, but revenue models ensure steady returns. The sector also benefits from partnerships with local governments, utilities, and automobile manufacturers. Strategic placement of EV charging stations maximizes usage and profitability. Innovative pricing models such as pay-per-use or monthly subscriptions attract diverse customer groups. Conversion services can generate income from labor charges, parts supply, and maintenance contracts. Recurring contracts with fleet operators and commercial clients ensure stable cash flow. Advances in battery technology and conversion kits lower costs and increase accessibility. Integration with smart grids and renewable energy sources enhances service value. Digital platforms and apps enable easy access, reservations, and payment, boosting usage. This guide explores ten business models that generate passive income in EV charging and conversion services. Each section offers practical strategies for sustainable revenue growth.

How Small Businesses Expanded Internationally with Limited Budgets

How Small Businesses Expanded Internationally with Limited Budgets

Expanding internationally is often seen as something only large corporations with millions of dollars can achieve, but small businesses across the globe have proven that with the right strategies, even limited budgets can take them across borders. Many entrepreneurs initially believe that entering foreign markets requires costly offices, legal teams, and advertising campaigns, but the digital era has changed that perception entirely. Through smart planning, resource optimization, and technology-driven approaches, local ventures have managed to tap into global markets with minimal investment. The secret lies not in money, but in creativity, research, and consistency. Entrepreneurs who succeed globally don’t waste resources—they leverage free or low-cost digital tools, government programs, outsourcing, and collaborations. For example, platforms like Shopify, Etsy, and Amazon have allowed small sellers to reach customers in dozens of countries without renting a single foreign store. Similarly, social media and content marketing have enabled unknown businesses to build trust and recognition in regions where big brands dominate. Instead of traditional expensive marketing campaigns, small businesses focused on niche targeting, personalized services, and unique value propositions. They built loyal customer bases by solving problems big companies often ignored. The most inspiring part is that these businesses did not wait for perfect conditions; they experimented, learned from failures, and grew gradually. This article explores real, step-by-step strategies small businesses used to expand internationally on a shoestring budget, showing how resourceful planning can beat financial limitations. By the end, you will see that you don’t need millions to go global—you just need the right roadmap and determination.

Hudson Global Now Star Equity Holdings – What Investors Need to Know

Hudson Global Now Star Equity Holdings – What Investors Need to Know

Why Rebranding Matters in Today’s Financial Market: In the world of finance, rebranding is not just a matter of logos, names, or colors—it’s about signaling transformation, repositioning strategy, and reshaping how a company communicates with its investors and stakeholders. The recent rebranding of Hudson Global into Star Equity Holdings has captured attention worldwide, particularly among investors seeking clarity on what this shift means for future growth, business direction, and shareholder value. Rebranding in corporate finance often goes beyond marketing; it is deeply tied to business realignment, mergers, acquisitions, or diversification into new markets. Investors are increasingly aware that a name change reflects broader structural moves, and Hudson Global’s evolution into Star Equity Holdings is no different. On September 2025, this news has generated search buzz as analysts, traders, and global audiences ask: Why now? and What’s next? Understanding the significance of this rebranding is crucial for those tracking investment opportunities and long-term financial strategies in today’s fast-changing market landscape.